ESMA 2026 sustainability reporting priorities: what you need to know

ESMA, the EU’s financial markets regulator and supervisor, has published the enforcement priorities (ECEP) for upcoming sustainability reports covering FY 2026.

ESMA makes one thing clear: regulators are moving beyond checking whether companies publish sustainability information and are now focusing on whether that information is material, connected, consistent, transparent and decision-useful.

For FY2026, ESMA’s sustainability priorities concentrate on two areas:

  1. Improving the quality of double materiality assessments (DMA) and IRO disclosures

  2. Strengthening the connections between IROs, policies, actions, targets and metrics (PATs)

The priorities outlined by ESMA provide useful guidance on where companies should focus their efforts in FY2026.


First: Understand the FY2026 Transition Rules

FY2026 is a transition year. Companies may prepare their sustainability statements using:

  • ESRS Set 1 2023 (as amended by the Quick Fix Regulation)

  • Revised ESRS 2026 (simplified ESRS)

  • ESRS Set 1 plus certain specific reliefs from revised ESRS 2026 allowed by Regulation (EU) 2026/1563.

What companies need to do

  • Clearly disclose which reporting framework was used.

  • Indicate the chosen framework in the “Basis for Preparation” section.

  • If using ESRS Set 1 with revised ESRS reliefs, only use the reliefs specifically listed in the regulation. No additional exemptions are permitted.

Taxonomy reminder

Although ESMA has not included specific EU Taxonomy recommendations this year because Taxonomy rules are under revision, regulators will continue reviewing Taxonomy disclosures. Companies should therefore not reduce attention to Taxonomy reporting.


Priority 1: Improve Double Materiality Assessment (DMA) and IRO Reporting

Why this matters

ESMA considers the DMA and the identification of Impacts, Risks and Opportunities (IROs) to be the foundation of the entire sustainability statement.

If the DMA is weak, everything built upon it becomes questionable.


1. Treat Positive and Negative Impacts Equally

A common issue identified by ESMA is that companies often describe positive impacts in great detail while providing limited information on negative impacts.

What to do

Instead of:

✅ Detailed discussion of social programs

❌ Little information on labour issues, emissions or negative impacts

Companies should provide:

  • equivalent analysis of positive impacts

  • equivalent analysis of negative impacts

  • balanced discussion of risks and opportunities

  • transparent rationale for materiality conclusions.

Practical test

Ask:

“Would a reader understand our major negative impacts as clearly as our positive contributions?”

If not, the disclosure probably needs improvement.


2. Be Transparent About Materiality Thresholds

Many companies use thresholds to determine which impacts are material.

ESMA expects companies to explain:

  • the thresholds used

  • how they were determined

  • whether different thresholds were applied to positive and negative impacts.

What good disclosure looks like

Instead of:

“The company assessed material impacts.”

Provide:

“An impact was considered material when severity exceeded X and affected more than Y stakeholders.”


3. Cover the Full Value Chain

A recurring issue is excessive focus on direct operations.

ESMA reminds companies that material impacts, risks and opportunities must include own operations, upstream value chain and downstream value chain.

Common mistake

Climate risks discussed only for owned facilities.

Better approach

Climate risks assessed across:

  • suppliers

  • transport

  • distribution

  • product use

  • end-of-life impacts

where relevant.


4. Make DMA Disclosures Topic-Specific

ESMA reminds us that information on the DMA process is most valuable when it is concise, company-specific and linked to the topic that is being assessed for material IROs.

Many companies have created generic descriptions of their DMA process.

ESMA recommends disclosures that explain how the assessment differs by topic.

Example

The process used to assess:

  • climate change

  • biodiversity

  • own workforce

  • human rights

may be different.

Explain those differences when they exist.


5. Use Entity-Specific Disclosures Sparingly

ESMA encourages companies to use ESRS categories whenever possible, to promote comparability across sustainability statements.

Entity-specific categories should only be used when ESRS does not adequately cover a material issue.

Ask before creating an entity-specific topic

Can this issue already be reported usingan ESRS topic or sub-topic?

If yes, use the ESRS structure.


Priority 2: Connect IROs, Policies, Actions, Targets and Metrics

This is perhaps the most important message in the 2026 priorities.

Many companies disclose:

  • IROs in one section

  • policies in another

  • actions elsewhere

  • targets in yet another section

without clearly linking them together.

ESMA expects a connected story.


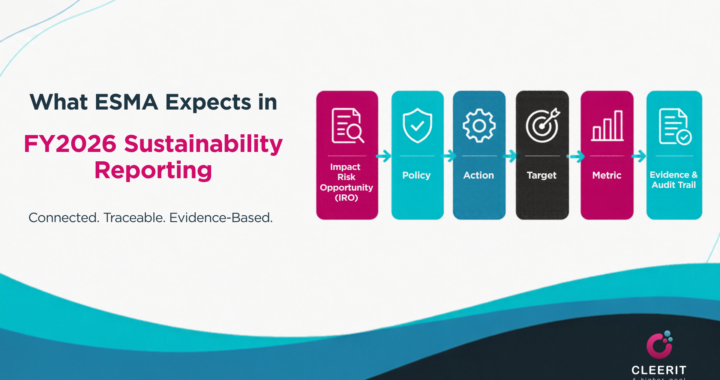
Build a Clear Chain of Logic – the IRO-response-logic.

For each material IRO, report users should understand:

The issue

What impact, risk or opportunity exists?

↓

The policy

What policy addresses it?

↓

The actions

What is the company doing?

↓

The target

What outcome is expected?

↓

The metric

How will progress be measured?


Example

IRO

Workplace discrimination risk

Policy

Human Rights and Equal Opportunity Policy

Actions

  • mandatory training

  • whistleblowing mechanism

  • supplier audits

Target

Reduce discrimination incidents by 50% by 2030

Metrics

  • number of incidents

  • training completion rate

  • remediation rate

This is the type of connectivity ESMA expects.


Explain Gaps

If a material IRO exists but there is:

  • no policy

  • no action

  • no target

you must say so.

Many companies try to hide such gaps.

ESMA explicitly requires transparency.


Clearly Explain Coverage Limitations

Another recurring issue is overstating coverage.

Example

A climate target addresses only Scope 1, Scope 2 but not Scope 3.

Companies should clearly explain the limitation.

Similarly:

If an IRO affects:

  • operations

  • suppliers

but actions only cover operations,

that fact should be disclosed.


Disclose Financial Resources

ESMA expects transparency regarding significant:

  • CapEx

  • OpEx

supporting sustainability actions.

Companies should explain

  • what resources are allocated

  • what actions they support

  • expected future investments

If major actions require little or no investment, companies should consider explaining why.


Ensure Consistency with Financial Reporting

ESMA found cases where:

  • sustainability risks appeared in the sustainability statement

  • but were absent from the Annual Financial Report

or vice versa.

Practical action

Cross-check:

  • material climate risks

  • supply chain risks

  • workforce risks

  • litigation risks

against:

  • principal risks section

  • management commentary

  • IFRS disclosures

The story should be consistent across the report.


Improve Year-on-Year Comparability

Comparability remains a major regulatory focus.

Companies should clearly explain

  • methodology changes

  • presentation changes

  • restatements

  • revised comparative figures

Example

If Scope 3 emissions increase because of improved data quality:

do not leave investors guessing.

Explain:

  • what changed

  • why it changed

  • how it affected reported performance.


Targets: One of the Biggest Regulatory Focus Areas

ESMA devotes considerable attention to targets.


Every Target Should Be:

Measurable

Bad:

“Improve diversity.”

Good:

“Increase women in leadership to 40% by 2030.”

Time-Bound

Include target dates.

Outcome-Oriented

Focus on outcomes rather than intentions.


Report Progress Honestly

If a target:

✅ has been achieved

say so.

✅ has been missed

say so.

✅ is unlikely to be achieved

say so.

✅ has been abandoned

say so.

ESMA is looking for transparency, not selective reporting.


Explain Methodological Changes

If you change:

  • baseline year

  • baseline value

  • target year

  • target value

  • calculation methodology

disclose and explain the change.

Example

A climate target originally used:

2020 baseline

Later revised to:

2022 baseline due to acquisition activity.

Investors should understand exactly how this affects reported progress.


Be Careful with “Science-Based” Claims

ESMA specifically criticises companies that state:

  • “science-based”

  • “1.5°C aligned”

without explaining why.

Companies should disclose

  • whether the target is science-based

  • how it is science-based

  • why it supports a 1.5°C pathway

Evidence is required.


Report Absolute Targets

Do not rely exclusively on intensity metrics.

Example:

❌ “20% reduction per unit produced”

✅ “500,000 tCO₂e to 300,000 tCO₂e”

ESMA expects disclosure of absolute values unless ESRS provides otherwise.


Distinguish Commitments from Targets

One issue ESMA observed frequently:

Companies blur the line between:

Commitments

“We aim to be an employer of choice.”

and

Targets

“Achieve employee engagement score of 80% by 2028.”

Targets must be measurable, time-bound and outcome-oriented.


The 2026 Checklist for Companies

Before finalising your sustainability statement, ask:

Governance

  • Have we disclosed which ESRS version we use?

  • Have we explained any reliefs applied?

DMA

  • Are positive and negative impacts assessed equally?

  • Have we disclosed materiality thresholds?

  • Are value-chain impacts included?

IROs

  • Are all material IROs clearly explained?

  • Are entity-specific disclosures justified?

Connectivity

  • Is every material IRO linked to policies, actions, targets and metrics?

  • Have we disclosed gaps?

Financial Effects

  • Have we connected sustainability risks with financial reporting?

  • Have we disclosed current financial effects where required?

Targets

  • Are targets measurable and time-bound?

  • Are progress and setbacks reported honestly?

  • Are methodological changes explained?

  • Are science-based claims substantiated?

  • Have we provided absolute values where required?

Comparability

  • Are restatements and revisions clearly disclosed?

  • Can users compare FY2026 with prior years?


Final Takeaway

The central message from ESMA is simple: sustainability reporting should tell a coherent, traceable and evidence-based story.

Material impacts, risks and opportunities must clearly connect to policies, actions, targets, metrics, financial effects and progress reporting.

Companies that can demonstrate these links clearly will be best positioned to meet regulatory expectations and build trust with investors, auditors and regulators.


From Regulatory Expectations to Operational Execution

ESMA’s 2026 enforcement priorities send a clear message: sustainability reporting is no longer a standalone compliance exercise.

Regulators increasingly expect companies to demonstrate clear links between material Impacts, Risks and Opportunities (IROs), policies, actions, targets and metrics, while ensuring consistency with financial reporting and maintaining robust audit trails.

The era of generic sustainability narratives is coming to an end. Companies must now provide evidence-based, traceable and decision-useful disclosures.

Meeting these expectations can be challenging. Many organisations struggle with fragmented data collection processes, inconsistent documentation, weak traceability between disclosures, and limited visibility over how sustainability information connects across the report.

This is where Cleerit can help.

Cleerit is designed to operationalise the full ESRS framework, enabling organisations to move from compliance-driven reporting to structured sustainability governance. The platform supports:

  • IRO-to-PATM connectivity, helping organisations create clear links between Impacts, Risks and Opportunities, Policies, Actions, Targets and Metrics.

  • Datapoint-level completeness and traceability, ensuring disclosures can be supported by documented evidence and audit-ready records.

  • Structured governance, workflows and controls, supporting the level of discipline increasingly expected by regulators, investors, lenders and ESG rating providers.

  • Machine-readable and audit-ready sustainability reporting, aligned with ESRS requirements and the growing role of AI-driven reviews, ESG ratings and digital assurance processes.

  • Consistent reporting across topics, metrics and reporting periods, helping organisations improve comparability and reduce the risk of gaps, inconsistencies and greenwashing concerns.

As ESMA’s priorities make clear, the companies best positioned for future reporting cycles will be those that can demonstrate not only what they report, but also how they arrived at their conclusions, how they monitor progress, and how sustainability information connects to strategy, risk management and financial performance.

By providing a structured ESRS architecture, audit-ready documentation and end-to-end traceability, Cleerit helps organisations build the governance, transparency and reporting quality required in an environment where sustainability information is increasingly scrutinised with the same rigour as financial reporting.

Ultimately, compliance is only the starting point. Companies that establish robust ESRS processes today will be better positioned to build trust with investors, maintain rating credibility, facilitate access to financing and create long-term business value.

Cleerit is built to help organisations achieve exactly that.

Source: https://www.esma.europa.eu/sites/default/files/2026-10/ESMA32-2064178921-9738_Statement_-_2026_European_Common_Enforcement_Priorities__ECEP_.pdf

Reducing greenwashing risk in sustainability communications: key lessons from ESMA

Sustainability claims increasingly influence investor decisions, customer trust and corporate reputation. At the same time, regulators are paying closer attention to the risk of greenwashing.

To support companies, ESMA, the EU’s financial markets regulator and supervisor, has recently published two new thematic notes offering practical advice on how to reduce the risk of greenwashing by ensuring non-regulatory sustainability communications are clear, fair and not misleading.

ESMA notes that sustainability claims may be misinterpreted and may mislead investors, even where this is not the intention of the company.

Key Takeaways

  • Show, don’t just claim impact
  • Support impact and transition claims with evidence
  • Explain assumptions, limitations and methodologies
  • Distinguish between outputs, outcomes and impact
  • Connect transition ambitions to implementation plans and measurable progress
  • Ensure consistency across all sustainability communications
  • Use ESRS-based reporting as the foundation for transparent, traceable and defensible sustainability claims

Impact claims

ESMA’s thematic note on impact claims is a practical warning against using “impact” language unless companies can clearly explain and evidence how that impact is created.

The note stresses that claims about creating positive environmental or social outcomes must be accurate, accessible, substantiated and up to date.

Companies should avoid vague statements such as “making a positive difference” or “delivering impact” unless they can articulate a clear impact objective, a credible theory of change, and measurable indicators showing progress.

Communications should clearly distinguish between

  • what the company or product intends to achieve (intentionality),
  • why its actions make a difference beyond what would have happened anyway (additionality), and
  • how outcomes are measured (measurability).

Cherry-picking data, relying on broad sustainability aspirations (e.g., SDG alignment alone), using impact terminology without evidence, or omitting limitations and assumptions are highlighted as common greenwashing risks.

The practical message is: show, don’t just claim.

If you communicate impact, explain the specific environmental or social problem being addressed, how your activities contribute to solving it, the criteria used to assess impact, and the KPIs used to monitor results.

Be transparent about whether metrics measure

  • outputs (activities undertaken),
  • outcomes (changes achieved), or
  • actual impact (real-world benefits).

Disclose key assumptions, data limitations and methodologies.

Avoid taking credit for outcomes that cannot reasonably be attributed to the company’s actions.

Ensure that all marketing, sustainability reports and other communications are consistent with one another.

Climate transition claims

ESMA’s thematic note on transition claims focuses on how to communicate climate transition ambitions without creating greenwashing risk.

The key message is that transition claims are inherently forward-looking and subject to uncertainty, as their achievement may depend on future actions, assumptions and external factors.

They therefore require a higher level of transparency than claims about current sustainability performance.

Don’t treat transition claims as a marketing narrative about future intentions.

The note highlights the importance of clearly communicating what the transition ambition is, how it is expected to be implemented and how progress will be assessed and communicated, including relevant assumptions, data limitations and dependencies.

Companies should clearly explain three elements:

  • the transition ambition (what is being achieved and by when),
  • the implementation strategy (how the ambition will be delivered), and
  • progress achieved (whether the company remains on track).

Any targets should include a baseline year, metrics, intermediate milestones and underlying assumptions, while references to net-zero, decarbonisation pathways, Paris alignment or science-based targets should be accompanied by explanations of what those concepts mean in the company’s specific context.

Broad aspirational statements without measurable objectives, methodologies or evidence are identified as a key greenwashing risk.

The practical recommendation is straightforward: every transition claim should be supported by evidence.

Explain how investments, projects, products or operational changes contribute to the stated transition objective, and disclose any material assumptions, dependencies and uncertainties.

Be transparent about exposure to high-emitting activities, the role of climate targets and transition plans, and the methodologies used to measure progress.

Report regularly against previously disclosed targets, use consistent metrics over time, disclose setbacks and explain changes in methodology instead of highlighting only positive developments.

Using ESRS as the foundation for transparent and defensible sustainability claims

ESMA’s guidance reinforces a trend that is becoming increasingly clear: sustainability communications can no longer be separated from sustainability reporting.

The requirements identified by ESMA closely mirror many of the principles embedded in ESRS reporting, including traceability, transparency, consistency and the use of measurable metrics and targets.

Companies that build their communications on robust ESRS data, transparent methodologies and documented evidence will be better positioned to avoid greenwashing risk and build trust with investors, customers and regulators.

Solutions such as Cleerit help organisations operationalise these requirements through

  • structured governance,
  • datapoint-level traceability,
  • audit-ready documentation and
  • clear linkages between impacts, policies, actions, targets and metrics,

creating a reliable foundation for credible sustainability claims.

Ultimately, the most effective defence against greenwashing is not better wording but better evidence. Companies that can clearly demonstrate how sustainability claims are supported by data, methodologies and measurable results will be best positioned to build trust with investors, customers and regulators.


Download ESMA’s thematic notes on positive impact and climate transition:

https://www.esma.europa.eu/press-news/esma-news/esma-promotes-clarity-claims-impact-and-transition

ESRS have now been published in the Official Journal of the European Union

The revised European Sustainability Reporting Standards (ESRS) have now been published in the Official Journal of the European Union: Commission Delegated Regulation (EU) 2026/1563).

This publication confirms the final text of the 2026 Delegated Act – the most significant simplification of EU sustainability reporting since the CSRD was adopted.

⭕ It is available here in all EU languages: Delegated regulation – EU – 2026/1563 – EN – EUR-Lex

⭕The Delegated Act reshapes ESRS in four major ways:

▪️ Fewer mandatory datapoints
▪️ Clearer, more practical materiality rules
▪️ Stronger interoperability
▪️ New reliefs and phase‑ins to reduce cost and complexity

This means: Substantial reporting cost savings. Shorter reports. Fewer tables. Clearer expectations. More decision‑useful information. And a framework that is simplified, more proportionate and better aligned with global standards.

⭕ Application timeline

▪️ 2026: Optional early adoption
▪️ 2027: Mandatory application for all undertakings in scope

⭕ Important timeline clarification

The publication of the Delegated Act does not trigger immediate entry into force in the Member States.

Under Article 29b of the Accounting Directive, the Delegated Act will enter into force on 10 November 2026 (four months after adoption on 3 July 2026).

It will be mandatory for financial years beginning on or after 1 January 2027.

For FY2026, undertakings may choose between:

▪️ the previous ESRS Set 1 (2023/2772 as amended),
▪️ the revised ESRS (2026/1563), or
▪️ the previous ESRS with selected new reliefs, provided they clearly state which version they apply.

⭕ In simplified ESRS, IRO management has taken center stage

The objective of an ESRS sustainability statement, taken as whole, is to present fairly all the company’s material sustainability-related impacts, risks and opportunities (IROs) and how it manages them. The reported information shall be decision-useful.

Companies should clearly show how each material IRO (or group of IROs) identified through the materiality assessment is managed through policies, actions, targets and metrics.

Too often, these elements are reported separately, making it difficult for readers to understand how the company’s responses address the material sustainability topics.

Integrating this IRO‑to‑response logic throughout the sustainability statement strengthens coherence, reduces duplication and ensures a well-structured decision-useful sustainability statement.

👉 If your first ESRS statement is due for FY2027, now is the moment to start. First wave reporters will already be several cycles ahead.


VS(ME) – Commission Delegated Regulation (EU) 2026/1560 of 3 July 2026 supplementing Directive 2013/34/EU of the European Parliament and of the Council by establishing sustainability reporting standards for voluntary use by undertakings protected by the value chain cap :

https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX%3A32026R1560

AI Governance and ESRS G1 Disclosures Using Cleerit and OECD Guidance

Companies are increasingly deploying AI in core operations, decision‑making, and customer‑facing services.

As this happens, ESRS G1 Business Conduct is a good place to demonstrate that governance systems, policies and disclosures can prevent misconduct, protect rights and ensure responsible behaviour.

To do so, AI‑related impacts and risks should be integrated into the relevant ESRS sub‑topics.

If AI is related to material impacts, risks or opportunities that are not covered, or not covered with sufficient granularity, by existing ESRS topics, AI should be added as an entity‑specific topic in accordance with revised ESRS 1 paragraph 11.

The OECD Due Diligence Guidance for Responsible AI provides a practical, internationally recognised framework that companies can use to build these systems.

This article translates the OECD guidance into concrete steps that companies can implement to strengthen governance and produce high‑quality ESRS G1 disclosures:

AI Governance and ESRS G1 Disclosures Using Cleerit and OECD Due Diligence Guidance for Responsible AI

To supports organisations throughout this process Cleerit offers a governance‑ready, compliant, efficient and ESRS‑aligned solution that makes responsible AI governance practical and manageable.

You are welcome to contact us for a demonstration >>>

EFRAG has released the 2026 Draft List of ESRS Datapoints

EFRAG has released the 2026 Draft List of ESRS Datapoints — a list of datapoints reflecting the Revised ESRS and underpinning the upcoming XBRL taxonomy

If you work with ESRS reporting, digital readiness, or sustainability data architecture, this release is worth your attention.

But before diving into the Excel file, it’s essential to understand how datapoints are defined according to the methodology described in the accompanying Explanatory Note.

The Draft List is built on a clear methodology that combines the structure of ESRS paragraphs with the underlying data type logic. Without understanding this foundation, the list can easily be misread.

Also keep in mind that a datapoint does not equal a fact. A “fact” is the actual piece of information the company discloses in an ESRS sustainability statement after applying the materiality filter — not the datapoint itself. Counting datapoints in an Excel list is therefore of limited relevance.

The Draft List is released as support material, not implementation guidance, nor a substitute for the standards themselves – and it is not a checklist.

It helps report preparers see how disclosures are structured, how datapoints are separated, and how they will connect to the upcoming XBRL taxonomy for digital reporting.

Users of the 2026 Draft List are advised to exercise their own judgment in applying ESRS, and EFRAG reminds users that the list should not be substituted for the services provided by an appropriately qualified professional.

👉 We have summarised the key points and practical implications for you in this note:

2026 Draft List of ESRS Datapoints – EFRAG 28 August 2026


Note that the information does not replace the information provided by EFRAG in the Explanatory note available here >>>


Have your say: take EFRAG’s online survey the 2026 Draft List of ESRS Datapoints

EFRAG Secretariat invites stakeholders to review the methodology used to compile the Draft List of ESRS Datapoints and to report any fatal flaws through the online survey by 23 October 2026.

The final resource is expected to be published by the end of 2026 following consideration of the feedback received.

Access the online survey here: https://survey.alchemer.eu/s3/91158320/Collecting-Feedback-on-Fatal-Flaws-in-the-Draft-List-of-Datapoints

Public consultation on ESRS-40a for non-EU undertakings with significant EU market activity

Have your say on ESRS-40a for non-EU undertakings with significant EU market activity

On July 23 EFRAG launched a 100-day public consultation on the Exposure Draft of the European Sustainability Reporting Standards (ESRS-40a ED) for certain non-EU undertakings, developed under Article 40a of the Accounting Directive.

All interested stakeholders are invited, both within and outside the EU, to share their views before 31 October, including on the practical implementation challenges and the relevance of the resulting disclosures.

The objective of the ESRS-40a sustainability report, taken as whole, is to present fairly all the parent undertaking or group’s material sustainability-related impacts, and how the parent undertaking or group manages them.

The aim is to ensure that there is a level playing field for undertakings operating in the EU market, as well as to ensure transparency on impacts on people and the environment of non-EU undertakings with relevant EU activities.

ESRS-40a standards were previously denominated in EFRAG preliminary documents as Non-EU ESRS (N-ESRS) or ESRS for third countries (ESRS-TC). By naming the standard ESRS‑40a, EFRAG makes the legal anchor visible and unambiguous. This reinforces that it is not a separate framework, but a CSRD‑mandated ESRS standard.

Click here to access the standard: ESRS-40a_Exposure_Draft.pdf

Click here to submit your feedback: EFRAG Launches Public Consultation on the ESRS-40a Exposure Draft for Certain Non-EU Undertakings | EFRAG


Who will be in-scope?

Non‑EU groups with >€450M EU turnover and at least one EU subsidiary or branch with >€200M EU turnover (no employee threshold) will need to publish an ESRS-40a sustainability report targeting financial years starting on or after January 1, 2028.

Around 1,200 companies are expected to fall in scope, including 350–450 US groups and 150–200 UK groups.

ESRS-40a is an impact‑only standard

Disclosures on risks, opportunities, financial effects and resilience are removed, because Article 40a legally limits the EU to requiring transparency on impacts on people and the environment (IFRS S1/S2 cover financial risks). However, companies may still include financial information when needed to explain. This is the core design choice: ESRS-40a = ESRS minus the financial‑materiality.

12 ESRS‑aligned standards

The standard requires disclosures across 12 ESRS‑aligned standards, covering strategy, governance, policies, targets, due diligence, impacts, actions and metrics.

Groups can choose between three reporting perimeters:

  • Global (default) — report global impacts for all topics
  • Mixed — EU‑related impacts only (but climate-related impacts are always global),
  • Full ESRS — voluntary, enabling subsidiary exemption if the non‑EU parent applies full ESRS

When assessing EU-related impacts, the following are examples of factors that the undertaking may consider:

  • (a) existence of a separate business segment dedicated to serving the EU market;
  • (b) products or services specifically designed for the EU-market;
  • (c) separate management of EU-related impacts; or
  • (d) value chains dedicated to products and services that were or can be reasonably assumed to be sold or provided in the EU market.

Timeline

Exposure Draft mid‑July 2026, consultation until October, technical advice in January 2027, adoption mid‑2027, first reports published in 2029 (on FY 2028).

ESRS-40a will reshape sustainability reporting for non‑EU groups with significant activities in the EU. Impact transparency becomes mandatory, global climate data collection will be essential, and early preparation is key.

New EU Oversight of ESG Ratings: Implications for CSR Communication and ESRS Reporting

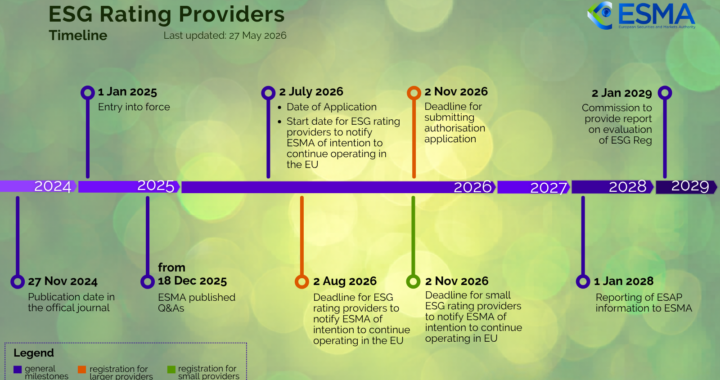
EU’s ESG Ratings Regulation (EU 2024/3005) came into effect on 2 July

In short:

EU’s new ESG Ratings Regulation introduces mandatory ESMA supervision of all ESG rating providers from 2 July 2026. The goal is to fix long‑standing issues of opacity, inconsistency and low reliability in ESG ratings that companies use in CSR, sustainability and investor communication. During the transition period (July–November 2026), companies may reference ESG ratings only if the provider has notified ESMA. From 2 November 2026, ratings may be used exclusively from providers that appear in ESMA’s Article 14 public register.

This creates new compliance checkpoints for companies: 

Before publishing annual reports, sustainability webpages or investor presentations, companies will need to verify the regulatory status of any ESG rating provider to ensure that referenced ratings come from transparent, supervised and trustworthy sources.

It also raises expectations for ESRS reporting quality. 

ESRS sustainability statements must be complete, traceable and audit‑ready, as ESG rating providers will increasingly cross‑check ESRS disclosures with their own supervised methodologies. Strong governance around sustainability data is essential – documenting sources, reinforcing controls and clarifying responsibilities.

At the same time, investors and assurance providers will apply greater scrutiny to data quality, methodological alignment and consistency between ESRS disclosures and any ESG ratings referenced.

Cleerit’s guided digital ESRS end‑to‑end templates and governance processes help organisations get a head start, avoid wasted effort and build the robust, well‑structured sustainability statements required under this new regulatory landscape.


What the ESGR Regulation mean for you

If you use ESG ratings in your communication, it is essential to understand that the ESG Ratings Regulation (EU 2024/3005) places all ESG rating providers under direct ESMA supervision to enhance transparency, integrity and comparability, and to reduce greenwashing risks. From 2 November 2026, companies may only reference ESG ratings from providers that have submitted their application or notification and appear in ESMA’s Article 14 public register.

ESMA will maintain this public register on its website, along with a transitional list (July–November 2026) of providers that have notified ESMA of their intention to apply. To avoid market disruption, ESMA confirms that third parties may continue publishing or distributing ESG ratings from notified providers between 2 July and ESMA’s decision on their application. This temporary list will be updated regularly until the full register goes live.

From 2 November 2026 onward, only ESG ratings from providers that have applied and are listed in the Article 14 register may be published or distributed. This ensures continuity for financial market participants while the new supervisory framework is phased in.

For CSRD/ESRS‑aligned communication, companies should integrate a provider‑status check into their publication workflow – especially for annual reports, sustainability webpages and investor presentations.

Why this regulation came to be

The ESGR Regulation was introduced because the ESG ratings market had grown rapidly and become highly influential, yet operated without EU‑level rules. The Commission identified persistent issues: low reliability and timeliness, opaque methodologies, unsolicited ratings, and a lack of oversight – all of which created risks for investors and rated companies.

ESMA supervision aims to make ESG ratings clearer, more consistent and more trustworthy, while supporting the EU’s broader sustainable‑finance architecture (Green Taxonomy, SFDR, CSRD).

What problems does it aim to resolve?

  1. Low reliability, accuracy, and timeliness of ratings

Investors and companies observed that ESG ratings often differed widely, were based on outdated data, or lacked clear justification.

  1. Lack of transparency in methodologies and data sources

Providers used very different approaches, often without disclosing how ratings were constructed or what data they relied on. This made ratings hard to interpret or compare.

  1. Unsolicited ratings and unclear provider practices

Companies were sometimes rated without engagement or visibility into the process, creating confusion and reputational risks.

  1. No oversight or control of rating providers

Before this regulation, ESG rating providers were not subject to EU rules on governance, conflicts of interest, or operational integrity.

  1. Consequences for markets and investors

These issues undermined investor confidence in sustainable products and created risks of misallocation of capital.

The EU’s objectives are clear:

  • Improve trust in ESG ratings and sustainable finance.
  • Ensure fair and transparent rating practices for companies.
  • Support the EU’s broader sustainable finance architecture (Green Taxonomy, SFDR, CSRD).
  • Create a level playing field for rating providers operating in the EU.

How the ESGR Regulation connects to ESRS and CSRD reporting

The link to ESRS is direct: ESRS disclosures feed ESG ratings, and ESG ratings shape how ESRS information is interpreted externally.

The ESGR Regulation governs how ESG ratings are produced and supervised, while ESRS governs how companies disclose their own sustainability information.

The ESGR Regulation aims to ensure ratings are “independent, impartial, systematic and of adequate quality”.

Rating providers must now disclose:

  • which E, S, G factors they use,
  • how they weight them,
  • what data limitations exist,
  • whether they assess financial materiality, impact materiality, or both.

Companies should expect their ESRS disclosures to be evaluated against these methodological choices, meaning that ESRS disclosures will be scrutinised more systematically and weaknesses will be reflected in ratings.

This creates new expectations for accuracy, traceability, and communication discipline. ESRS disclosures must be reliable because ESG ratings will become more reliable.

For companies, this raises the bar for ESRS reporting quality.

Your ESRS sustainability statement must be well structured, complete, traceable and audit‑ready, as rating providers will rely more heavily on ESRS disclosures – and will be supervised by ESMA.

Strong governance around sustainability data is essential – documenting sources, reinforcing controls and clarifying responsibilities.

Investors and assurance providers will also apply greater scrutiny to data quality, methodological alignment and consistency between ESRS disclosures and any ESG ratings referenced.

New criteria to stop companies from making misleading sustainability claims including through ESG Credentials

In parallel, the European Union is also targeting greenwashing and forcing companies to prove their environmental impact in other ways. The Empowering Consumers for the Green Transition Directive (ECGT) will become fully enforceable on September 27, 2026, banning generic claims like “eco-friendly” or “green” without proof (https://eur-lex.europa.eu/eli/dir/2024/825/oj/eng).

ESMA has also recently published two thematic notes on clear, fair & not misleading sustainability-related claims, addressing greenwashing risks in support of sustainable investments (see one of the notes enclosed). They specifically targeted ESG Credentials:

  1. References to ESG credentials are among the most prominently used claims in retail-investor focused communications. These include references to qualifications, labels, ratings, certificates (henceforth referred to as “ESG credentials”): and can be misleading in several ways. For instance, by overstating the significance of having a given label, of receiving an ESG award, of being signatory to a voluntary framework, etc.
  1. Notably, these claims are of relevance for the following parties: fund managers (claims about funds’ and asset managers’ credentials), benchmark administrators (benchmarks’ credentials), investment service providers (claims at entity and/or product level) and issuers (entity-level claims).
  1. The ESG credential claim types below are considered in particular:
  • a) Industry initiatives: actual significance of market participants’ involvement in net zero alliances, in voluntary ESG initiatives, including doing voluntary ESG reporting under specific international frameworks. Sometimes, being a signatory to some of these initiatives leads to receiving an external ESG rating/assessment from the third party, which may be based on self-reported ESG information.
  • b) Labels and awards: actual significance of having a given credential like a national or regional label or perceived labels or of having won any type of ESG award (such as sustainability reporting awards for issuers); and
  • c) Comparisons to peers: actual significance of ESG credentials that are based on comparing ESG characteristics of a product or an entity (including ESG metrics like carbon footprint, ESG ratings, etc.) to competitors, peer groups, etc. Very often, it is not clear whether a credential is absolute or whether it is based on a comparison to peers.

How to prepare

A well‑structured, machine‑readable ESRS statement not only ensures ESG rating readiness – it strengthens governance, accelerates internal learning, reveals strategic blind spots and positions your organisation for the EU’s dual green and digital transition.

If your first ESRS report is due for FY2027, remember: early reporters will already be on their fourth cycle. Building processes, collecting data, and aligning teams takes time. Waiting until 2027 means falling years behind, so starting now is essential.

👉 Cleerit’s guided digital ESRS end‑to‑end templates and governance processes help you get a head start by saving time, avoiding wasted effort and ensuring a higher‑quality, more trustworthy sustainability statement. Contact us here >>>


Sources:

Regulation (EU) 2024/3005 on the transparency and integrity of Environmental, Social and Governance (ESG) rating activities: https://eur-lex.europa.eu/eli/reg/2024/3005/oj/eng

ESMA rules for ESG rating providers: https://www.esma.europa.eu/esmas-activities/investors-and-issuers/esg-rating-providers

Public Statement from ESMA on what third parties may legally do with ESG ratings during the transition to the new EU ESG Ratings Regulation: https://www.esma.europa.eu/sites/default/files/2026-07/ESMA84-1427279869-1396_Public_Statement_on_Publication_or_distribution_of_ESG_ratings_by_third_parties_in_the_period_from_2_July_2026_until_authorisation__recogniti.pdf

ESMA’s thematic notes on clear, fair & not misleading sustainability-related claims addressing greenwashing risks in support of sustainable investments : ESMA36-429234738_-154_Thematic_notes_on_clear__fair___not_misleading_sustainability-related_claims.pdf

Today the European Commission adopted the revised ESRS

The EU has just reshaped sustainability reporting.

Today, on 3 July 2026, the European Commission adopted the revised ESRS — the biggest update since CSRD came into force. The new Delegated Act cuts mandatory datapoints by 61%, strengthens interoperability with ISSB and the EU Taxonomy, and clarifies how materiality should be applied in practice.

For companies preparing their next sustainability report, this is a turning point:

  • Optional early adoption in 2026
  • Mandatory application from 2027
  • New reliefs, clearer rules, and lower reporting burden
  • Stronger focus on standardized, decision‑useful, material information

Below we have summarized the key changes — and what they mean for your reporting processes.

You can download the revised ESRS here: https://ec.europa.eu/finance/docs/level-2-measures/csrd-delegated-act-2026-5010-annex_en.pdf

The EU Accounting Directive (link below) contains two independent conditions that must both be satisfied before ESRS delegated acts can officially enter into force.

  • Scrutiny period completed (Article 49), minimum two months, maximum 4 months
  • Minimum four‑month delay after adoption (Article 29b)

The earliest possible entry‑into‑force date is therefore determined by whichever of these two periods ends later.

So, in practice,

  • if the scrutiny period ends before four months, the act still waits until the four‑month minimum has expired;
  • if the scrutiny period is extended to four months, both periods end at the same time.

In this case, this means that the expected official entry into force of revised ESRS is 10 November even though the scrutiny period ended on 3 September and was not extended (3 November 2026 since the adoption was 3 July 2026, and after that, the act still needs publication in the Official Journal, usually adding a few days).

https://eur-lex.europa.eu/legal-content/EN/TXT/?uri=CELEX%3A02013L0034-20260318


The 2026 CSRD Delegated Act: What You Need to Know for Your Next Sustainability Report

On 3 July 2026, the European Commission adopted a major update to the European Sustainability Reporting Standards (ESRS). This Delegated Act simplifies the reporting framework, reduces mandatory datapoints, and clarifies how companies should apply materiality. It is the most significant revision since ESRS was first introduced in 2023—and it directly affects how companies will report from financial year 2027, with optional early adoption in 2026.

  1. Why the ESRS were revised

The revision is part of the Omnibus I simplification package, which aims to reduce administrative burden while preserving the core objectives of the CSRD. The Commission explains that the update was needed to:

“remove datapoints deemed least important… prioritise quantitative datapoints… further distinguish between mandatory and voluntary datapoints… and provide clear instructions on how to apply the materiality principle.”

The goal is to make sustainability reporting simpler, clearer, and more proportionate, especially for companies with complex value chains.

  1. When the new standards apply

The Delegated Act states:

“Undertakings must use the revised ESRS from financial year 2027. They may choose to use the revised ESRS also for financial year 2026.”

Timeline

  • 2026: Optional early adoption
  • 2027: Mandatory application for all companies in scope
  • Entry into force: Four months + one week after adoption at the latest (≈ November 2026)

Companies reporting for FY2026 must explicitly state which version of ESRS they apply.

  1. Key simplifications companies will notice

3.1 Fewer mandatory datapoints (‑61%)

EFRAG’s technical advice led to a dramatic reduction in mandatory disclosures:

“Reducing the mandatory datapoints by 61% while retaining the core objectives of the European Green Deal.”

This means shorter reports, fewer tables, and more focus on what is truly material.

3.2 Clearer and more practical materiality rules

Materiality is the central mechanism for determining what to report.

The Commission clarifies that companies:

“shall not report information that is not material, except in certain clearly defined circumstances.”

New guidance includes:

  • A top‑down approach allows the undertaking to avoid unnecessary work and in general to avoid assessing the materiality of each individual impact, risk or opportunity.
  • Explicit permission to omit information that is commercially sensitive.
  • More flexibility regarding the need to consider specific geographical contexts when carrying out the materiality assessment – also clarifies that the level of disaggregation for materiality assessment does not imply that information must be reported at that same level of disaggregation.
  • The text states that reporting anticipated financial effects is likely to involve estimates and that these can be updated in the future in light of new information without this constituting a reporting “error” – and an additional year of phasing-in is introduced for both qualitative and quantitative information.
  • Reliefs for undue cost or effort and value chain limitations

3.3 More interoperability with global standards

The revised ESRS improves alignment with:

  • ISSB standards
  • EU Taxonomy
  • CSDDD (Corporate Sustainability Due Diligence Directive)

For example, companies may now use either financial control or operational control when defining GHG reporting boundaries—matching global practice.

3.4 New reliefs and phase‑ins

Companies get additional flexibility, including:

  • Extra year of phase‑in for anticipated financial effects
  • One‑year phase‑in for substances of very high concern
  • Reliefs for new acquisitions, joint operations, and non‑significant activities

These changes reduce the risk of non‑compliance and lower implementation costs.

  1. What remains mandatory

Despite simplification, several core areas remain essential:

  • Double materiality and reporting on IROs, policies, actions, targets and metrics
  • Climate transition plans (with transparency if not aligned with 1.5°C)
  • Primary microplastics disclosures
  • Pollutant emissions (based on managerial assessment)
  • Human rights incidents (only “substantiated verified” cases)

The Commission emphasizes that simplification must not undermine the European Green Deal.

  1. Expected cost savings

EFRAG’s cost‑benefit analysis shows substantial reductions:

“Reporting cost savings correspond on average to 34% of baseline costs… cumulative savings raise to around EUR 4.7 billion over 2027–2031.”

This is one of the strongest signals that ESRS aim to become more manageable for companies.

  1. What to do now

Step 1 — Decide whether to adopt early (FY2026)

Early adoption may simplify your 2026 report, but requires clear disclosure of the chosen ESRS version.

Step 2 — Update internal reporting systems

The revised ESRS structure is simpler, but companies must ensure:

  • updated templates
  • updated data models
  • updated governance and controls
  • alignment with CSDDD and EU Taxonomy, if applicable
  1. Final takeaway

The 2026 Delegated Act marks a turning point and the end of a long period of uncertainty. ESRS becomes more proportionate, more aligned with global standards, and significantly easier to understand and implement. Companies that embrace the materiality‑driven standardized reporting approach will produce shorter, clearer, and more decision‑useful sustainability reports—with lower cost and less administrative burden.

A well‑structured, machine‑readable sustainability statement also strengthens governance, accelerates internal learning, reveals strategic blind spots, and positions your organization for the EU’s dual green and digital transition.

If your first ESRS report is due in FY2027, remember: early reporters will already be on their fourth cycle. Building processes, collecting data, and aligning teams takes time. Waiting until 2027 means falling years behind. Now is the time to start.

👉 Contact us if you want to use our guided digital ESRS end-to-end templates to get a head start.

Source: Commission adopts revised sustainability reporting standards to reduce administrative burdens for EU businesses while maintaining high-quality disclosures – Finance

Summary of the EFRAG State of Play 2026 Report

EFRAG’s second State of Play edition, based on the FY2025 reporting cycle, analyses 905 assured FY2025 sustainability statements, offering the most comprehensive evidence to date of how companies are applying ESRS in their second CSRD reporting year.

The findings show continuity with refinement, not structural transformation.

The message is clear: ESRS reporting is becoming more consistent and evidence-based. The next frontier is strengthening the link between materiality, measurable targets, and strategic decision-making.

Geographies and sectors in scope

The FY2025 sample shows a shift in which countries are most represented in the sustainability reports analysed. Last year, France, Germany, and Finland had the largest share. This year, Sweden is in the lead (14%), followed by Germany (12%) and France (11%). There is also a strong Nordic increase, with Norway growing from 2% to 7% of the sample.

However, the report warns that these numbers are partially influenced by the cut-off date (20 April 2026). Some countries publish their reports (especially English versions) later in the year, so they are under‑represented in this dataset.

Among the non-financial companies, Manufacturing remains by far the largest sector, accounting for 36% of the entire baseline.

Cross-cutting insights

  • Materiality remains stable: Companies report on average 6.4 material topics, with E1 Climate Change, S1 Own Workforce, and G1 Business Conduct material for >95% of undertakings.
  • DMA methodology: 67% use a hybrid approach combining the benefits of bottom-up and top-down analysis for different topics. 82% updated their DMA since FY2024 through modifications ranging from minor refinements to scope changes.
  • IROs: Companies disclose ~30 IROs, heavily concentrated in E1 and S1 followed by G1 (60%). At country level, Spain leads with an average of 44 total IROs per company followed by Italy with 40 IROs and France at 35 while Sweden is positioned at 24 IROs. IROs are a key component of double materiality assessment, helping companies to determine which sustainability topics they should report on, and to identify how their business affects people and the environment (impacts), and how sustainability matters are material from a financial perspective.
  • Targets & incentives: Only 50% of material topics have measurable targets and 63% embed sustainability in executive remuneration, revealing a widening discrepancy between declared materiality and strategic commitment. At country level, France leads with 4 average number of material topics with targets.
  • Structure: Sustainability disclosures represent 34% of annual report length. Only 6% include an executive summary.

Environmental standards

  • Climate Transition Plans: Adoption increased from 55% to 69%, reflecting continued momentum in corporate climate planning.
  • 1.5°C alignment: 57% disclose near‑ and long‑term targets compatible with 1.5°C.
  • Non-climate topics (E2–E5): Slight rise in materiality. However, 77% report metrics only at global level, with minimal geographic disaggregation at regional and site level.

Social standards

  • Gender pay gap: Average unadjusted gap is 14.3% in favor of men, with the widest gaps concentrated in the financial sector. Only 12% of companies have enriched this figure with the adjusted pay gap to better account for the particularities of their workforce (i.e. geographic distribution and roles of their employees across the undertaking). At country level, Belgium has the lowest gap (7.7%) followed by Finland (10.7%) and Sweden (12.5%).
  • Discrimination & human rights incidents: Disclosure is high (85% and 93% respectively).
  • Human rights policies: 89% have policies covering Workers in the Value Chain and/or Affected Communities.

Governance (G1)

  • Materiality: a slight increase with Supplier relationship management, including payment practices, material for 54% of the undertakings vs. 50% in FY2024.
  • Supplier ESG criteria: 81% reference ESG criteria, but the nature of that integration is predominantly declarative – mostly via codes of conduct – operational integration remains limited.
  • SME payment terms: Only 7% disclose SME-specific terms. Average SME payment term is 24 days. This requirement has proved particularly challenging given – amongst others – the limitations of standard ERP systems in segmenting supplier data by company size.

If your first ESRS report is due in FY2027, remember: early reporters will already be on their fourth cycle. Building processes, collecting data, and aligning teams takes time. Waiting until 2027 means falling years behind.

—

🌿 A well‑structured, machine‑readable sustainability statement strengthens governance, accelerates internal learning, reveals strategic blind spots, and positions your organization for the EU’s dual green and digital transition.

👉 Contact us if you want to use our guided digital ESRS end-to-end templates to get a head start.
 

Read the full report from EFRAG here: EFRAG_State of Play 2026_vShared_Layout checked – DD.pdf

Understanding Eligible, Aligned, Enabling & Transitional economic activities under the EU Green Taxonomy

One of the most common sources of confusion in Article 8 reporting is the distinction between eligible, aligned, enabling, and transitional KPIs (i.e., Turnover, CapEx and OpEx).

Here is a breakdown:

⭕ Eligible activity – is “in scope”

Turnover (or CapEx or OpEx) is eligible when it comes from an economic activity listed in the EU Taxonomy (i.e., it appears in the Climate Delegated Act or Environmental Delegated Act), regardless of whether the company meets the technical screening criteria.

➡️ Eligibility = in scope, not green. It is the first filter in Article 8: companies must disclose the share of turnover, CapEx, OpEx associated with Taxonomy‑eligible activities before assessing alignment.

⭕ Aligned activity – is “fully compliant”

Turnover (or CapEx or OpEx) is aligned when the activity:

🌿 Substantially contributes to one EU environmental objective

🌿 Does no significant harm to the other environmental objectives

🌿 Complies with the technical screening criteria

🌿 Meets minimum safeguards (on an enterprise level)

➡️ Alignment = fully Taxonomy‑compliant. This is the KPI investors look at to understand how “green” a company truly is.

⭕ Enabling activity – “makes others green”

Enabling activities generate turnover (or CapEx or OpEx) by helping other activities achieve substantial contribution (e.g., components for wind turbines, low‑carbon inputs). They are not green on their own, but they are essential to green outcomes.

➡️ Enabling activities are a subset of aligned activities – not an alternative.

Financial products must disclose enabling activities separately.

⭕ Transitional activity – is “on the pathway”

Transitional activities apply where no low‑carbon alternative exists yet, but the activity is on a credible decarbonisation pathway. They must:

▪️ Have lower emissions than the sector average
▪️ Avoid lock‑in
▪️ Not hinder low‑carbon alternatives
▪️ Tighten criteria over time

➡️ Transitional = necessary interim activities on the path to net zero. Also disclosed separately in financial product reporting.

👉 How they fit together in Article 8 KPI reporting:

▪️ Eligible = activity appears in the Taxonomy

▪️ Aligned = meets all SC + DNSH + safeguards + TSC

▪️ Enabling = subset of aligned

▪️ Transitional = subset of aligned

Enabling and transitional activities do not replace alignment – they refine it.

—

🌿 A well‑structured, machine‑readable sustainability statement strengthens governance, accelerates internal learning, reveals strategic blind spots, and positions your organization for the EU’s dual green and digital transition.

👉 Contact us if you want to use our guided digital ESRS end-to-end templates to get a head start.