ESMA, the EU’s financial markets regulator and supervisor, has published the enforcement priorities (ECEP) for upcoming sustainability reports covering FY 2026.
ESMA makes one thing clear: regulators are moving beyond checking whether companies publish sustainability information and are now focusing on whether that information is material, connected, consistent, transparent and decision-useful.
For FY2026, ESMA’s sustainability priorities concentrate on two areas:
-
Improving the quality of double materiality assessments (DMA) and IRO disclosures
-
Strengthening the connections between IROs, policies, actions, targets and metrics (PATs)
The priorities outlined by ESMA provide useful guidance on where companies should focus their efforts in FY2026.
First: Understand the FY2026 Transition Rules
FY2026 is a transition year. Companies may prepare their sustainability statements using:
-
ESRS Set 1 2023 (as amended by the Quick Fix Regulation)
-
Revised ESRS 2026 (simplified ESRS)
-
ESRS Set 1 plus certain specific reliefs from revised ESRS 2026 allowed by Regulation (EU) 2026/1563.
What companies need to do
-
Clearly disclose which reporting framework was used.
-
Indicate the chosen framework in the “Basis for Preparation” section.
-
If using ESRS Set 1 with revised ESRS reliefs, only use the reliefs specifically listed in the regulation. No additional exemptions are permitted.
Taxonomy reminder
Although ESMA has not included specific EU Taxonomy recommendations this year because Taxonomy rules are under revision, regulators will continue reviewing Taxonomy disclosures. Companies should therefore not reduce attention to Taxonomy reporting.
Priority 1: Improve Double Materiality Assessment (DMA) and IRO Reporting
Why this matters
ESMA considers the DMA and the identification of Impacts, Risks and Opportunities (IROs) to be the foundation of the entire sustainability statement.
If the DMA is weak, everything built upon it becomes questionable.
1. Treat Positive and Negative Impacts Equally
A common issue identified by ESMA is that companies often describe positive impacts in great detail while providing limited information on negative impacts.
What to do
Instead of:
✅ Detailed discussion of social programs
❌ Little information on labour issues, emissions or negative impacts
Companies should provide:
-
equivalent analysis of positive impacts
-
equivalent analysis of negative impacts
-
balanced discussion of risks and opportunities
-
transparent rationale for materiality conclusions.
Practical test
Ask:
“Would a reader understand our major negative impacts as clearly as our positive contributions?”
If not, the disclosure probably needs improvement.
2. Be Transparent About Materiality Thresholds
Many companies use thresholds to determine which impacts are material.
ESMA expects companies to explain:
-
the thresholds used
-
how they were determined
-
whether different thresholds were applied to positive and negative impacts.
What good disclosure looks like
Instead of:
“The company assessed material impacts.”
Provide:
“An impact was considered material when severity exceeded X and affected more than Y stakeholders.”
3. Cover the Full Value Chain
A recurring issue is excessive focus on direct operations.
ESMA reminds companies that material impacts, risks and opportunities must include own operations, upstream value chain and downstream value chain.
Common mistake
Climate risks discussed only for owned facilities.
Better approach
Climate risks assessed across:
-
suppliers
-
transport
-
distribution
-
product use
-
end-of-life impacts
where relevant.
4. Make DMA Disclosures Topic-Specific
ESMA reminds us that information on the DMA process is most valuable when it is concise, company-specific and linked to the topic that is being assessed for material IROs.
Many companies have created generic descriptions of their DMA process.
ESMA recommends disclosures that explain how the assessment differs by topic.
Example
The process used to assess:
-
climate change
-
biodiversity
-
own workforce
-
human rights
may be different.
Explain those differences when they exist.
5. Use Entity-Specific Disclosures Sparingly
ESMA encourages companies to use ESRS categories whenever possible, to promote comparability across sustainability statements.
Entity-specific categories should only be used when ESRS does not adequately cover a material issue.
Ask before creating an entity-specific topic
Can this issue already be reported usingan ESRS topic or sub-topic?
If yes, use the ESRS structure.
Priority 2: Connect IROs, Policies, Actions, Targets and Metrics
This is perhaps the most important message in the 2026 priorities.
Many companies disclose:
-
IROs in one section
-
policies in another
-
actions elsewhere
-
targets in yet another section
without clearly linking them together.
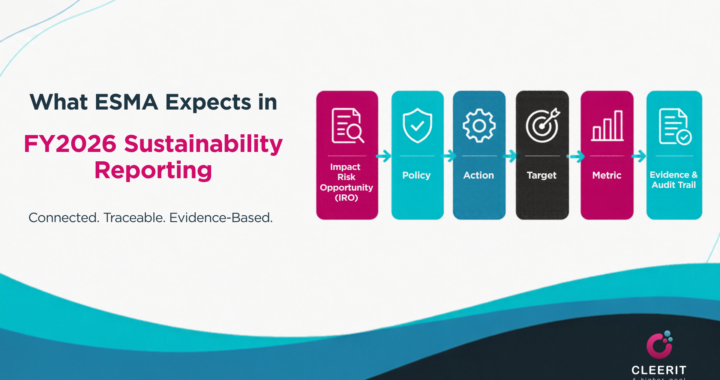
ESMA expects a connected story.
Build a Clear Chain of Logic – the IRO-response-logic.
For each material IRO, report users should understand:
The issue
What impact, risk or opportunity exists?
↓
The policy
What policy addresses it?
↓
The actions
What is the company doing?
↓
The target
What outcome is expected?
↓
The metric
How will progress be measured?
Example
IRO
Workplace discrimination risk
Policy
Human Rights and Equal Opportunity Policy
Actions
-
mandatory training
-
whistleblowing mechanism
-
supplier audits
Target
Reduce discrimination incidents by 50% by 2030
Metrics
-
number of incidents
-
training completion rate
-
remediation rate
This is the type of connectivity ESMA expects.
Explain Gaps
If a material IRO exists but there is:
-
no policy
-
no action
-
no target
you must say so.
Many companies try to hide such gaps.
ESMA explicitly requires transparency.
Clearly Explain Coverage Limitations
Another recurring issue is overstating coverage.
Example
A climate target addresses only Scope 1, Scope 2 but not Scope 3.
Companies should clearly explain the limitation.
Similarly:
If an IRO affects:
-
operations
-
suppliers
but actions only cover operations,
that fact should be disclosed.
Disclose Financial Resources
ESMA expects transparency regarding significant:
-
CapEx
-
OpEx
supporting sustainability actions.
Companies should explain
-
what resources are allocated
-
what actions they support
-
expected future investments
If major actions require little or no investment, companies should consider explaining why.
Ensure Consistency with Financial Reporting
ESMA found cases where:
-
sustainability risks appeared in the sustainability statement
-
but were absent from the Annual Financial Report
or vice versa.
Practical action
Cross-check:
-
material climate risks
-
supply chain risks
-
workforce risks
-
litigation risks
against:
-
principal risks section
-
management commentary
-
IFRS disclosures
The story should be consistent across the report.
Improve Year-on-Year Comparability
Comparability remains a major regulatory focus.
Companies should clearly explain
-
methodology changes
-
presentation changes
-
restatements
-
revised comparative figures
Example
If Scope 3 emissions increase because of improved data quality:
do not leave investors guessing.
Explain:
-
what changed
-
why it changed
-
how it affected reported performance.
Targets: One of the Biggest Regulatory Focus Areas
ESMA devotes considerable attention to targets.
Every Target Should Be:
Measurable
Bad:
“Improve diversity.”
Good:
“Increase women in leadership to 40% by 2030.”
Time-Bound
Include target dates.
Outcome-Oriented
Focus on outcomes rather than intentions.
Report Progress Honestly
If a target:
✅ has been achieved
say so.
✅ has been missed
say so.
✅ is unlikely to be achieved
say so.
✅ has been abandoned
say so.
ESMA is looking for transparency, not selective reporting.
Explain Methodological Changes
If you change:
-
baseline year
-
baseline value
-
target year
-
target value
-
calculation methodology
disclose and explain the change.
Example
A climate target originally used:
2020 baseline
Later revised to:
2022 baseline due to acquisition activity.
Investors should understand exactly how this affects reported progress.
Be Careful with “Science-Based” Claims
ESMA specifically criticises companies that state:
-
“science-based”
-
“1.5°C aligned”
without explaining why.
Companies should disclose
-
whether the target is science-based
-
how it is science-based
-
why it supports a 1.5°C pathway
Evidence is required.
Report Absolute Targets
Do not rely exclusively on intensity metrics.
Example:
❌ “20% reduction per unit produced”
✅ “500,000 tCO₂e to 300,000 tCO₂e”
ESMA expects disclosure of absolute values unless ESRS provides otherwise.
Distinguish Commitments from Targets
One issue ESMA observed frequently:
Companies blur the line between:
Commitments
“We aim to be an employer of choice.”
and
Targets
“Achieve employee engagement score of 80% by 2028.”
Targets must be measurable, time-bound and outcome-oriented.
The 2026 Checklist for Companies
Before finalising your sustainability statement, ask:
Governance
-
Have we disclosed which ESRS version we use?
-
Have we explained any reliefs applied?
DMA
-
Are positive and negative impacts assessed equally?
-
Have we disclosed materiality thresholds?
-
Are value-chain impacts included?
IROs
-
Are all material IROs clearly explained?
-
Are entity-specific disclosures justified?
Connectivity
-
Is every material IRO linked to policies, actions, targets and metrics?
-
Have we disclosed gaps?
Financial Effects
-
Have we connected sustainability risks with financial reporting?
-
Have we disclosed current financial effects where required?
Targets
-
Are targets measurable and time-bound?
-
Are progress and setbacks reported honestly?
-
Are methodological changes explained?
-
Are science-based claims substantiated?
-
Have we provided absolute values where required?
Comparability
-
Are restatements and revisions clearly disclosed?
-
Can users compare FY2026 with prior years?
Final Takeaway
The central message from ESMA is simple: sustainability reporting should tell a coherent, traceable and evidence-based story.
Material impacts, risks and opportunities must clearly connect to policies, actions, targets, metrics, financial effects and progress reporting.
Companies that can demonstrate these links clearly will be best positioned to meet regulatory expectations and build trust with investors, auditors and regulators.
From Regulatory Expectations to Operational Execution
ESMA’s 2026 enforcement priorities send a clear message: sustainability reporting is no longer a standalone compliance exercise.
Regulators increasingly expect companies to demonstrate clear links between material Impacts, Risks and Opportunities (IROs), policies, actions, targets and metrics, while ensuring consistency with financial reporting and maintaining robust audit trails.
The era of generic sustainability narratives is coming to an end. Companies must now provide evidence-based, traceable and decision-useful disclosures.
Meeting these expectations can be challenging. Many organisations struggle with fragmented data collection processes, inconsistent documentation, weak traceability between disclosures, and limited visibility over how sustainability information connects across the report.
This is where Cleerit can help.
Cleerit is designed to operationalise the full ESRS framework, enabling organisations to move from compliance-driven reporting to structured sustainability governance. The platform supports:
-
IRO-to-PATM connectivity, helping organisations create clear links between Impacts, Risks and Opportunities, Policies, Actions, Targets and Metrics.
-
Datapoint-level completeness and traceability, ensuring disclosures can be supported by documented evidence and audit-ready records.
-
Structured governance, workflows and controls, supporting the level of discipline increasingly expected by regulators, investors, lenders and ESG rating providers.
-
Machine-readable and audit-ready sustainability reporting, aligned with ESRS requirements and the growing role of AI-driven reviews, ESG ratings and digital assurance processes.
-
Consistent reporting across topics, metrics and reporting periods, helping organisations improve comparability and reduce the risk of gaps, inconsistencies and greenwashing concerns.
As ESMA’s priorities make clear, the companies best positioned for future reporting cycles will be those that can demonstrate not only what they report, but also how they arrived at their conclusions, how they monitor progress, and how sustainability information connects to strategy, risk management and financial performance.
By providing a structured ESRS architecture, audit-ready documentation and end-to-end traceability, Cleerit helps organisations build the governance, transparency and reporting quality required in an environment where sustainability information is increasingly scrutinised with the same rigour as financial reporting.
Ultimately, compliance is only the starting point. Companies that establish robust ESRS processes today will be better positioned to build trust with investors, maintain rating credibility, facilitate access to financing and create long-term business value.
Cleerit is built to help organisations achieve exactly that.